


With Anthropic launching its roadshow and announcing its price range, we now have enough information to build a rough model for the company, give our view on the IPO, and start our coverage.
Undoubtedly, this will be the litmus test for the AI trade. While SpaceX had a slightly bigger IPO (where we nailed the IPO trade), it rode on the hype of space data centers, Starlink potential, and obviously Musk’s personality. Anthropic will be different— they are IPO’ing into a weak market for the AI trade and a hostile political atmosphere.
This might have inadvertently worked in our favor. The company had planned to list at a $2 trillion valuation a few months ago, but cooling market conditions mean they are targeting ~$1.3 trillion.
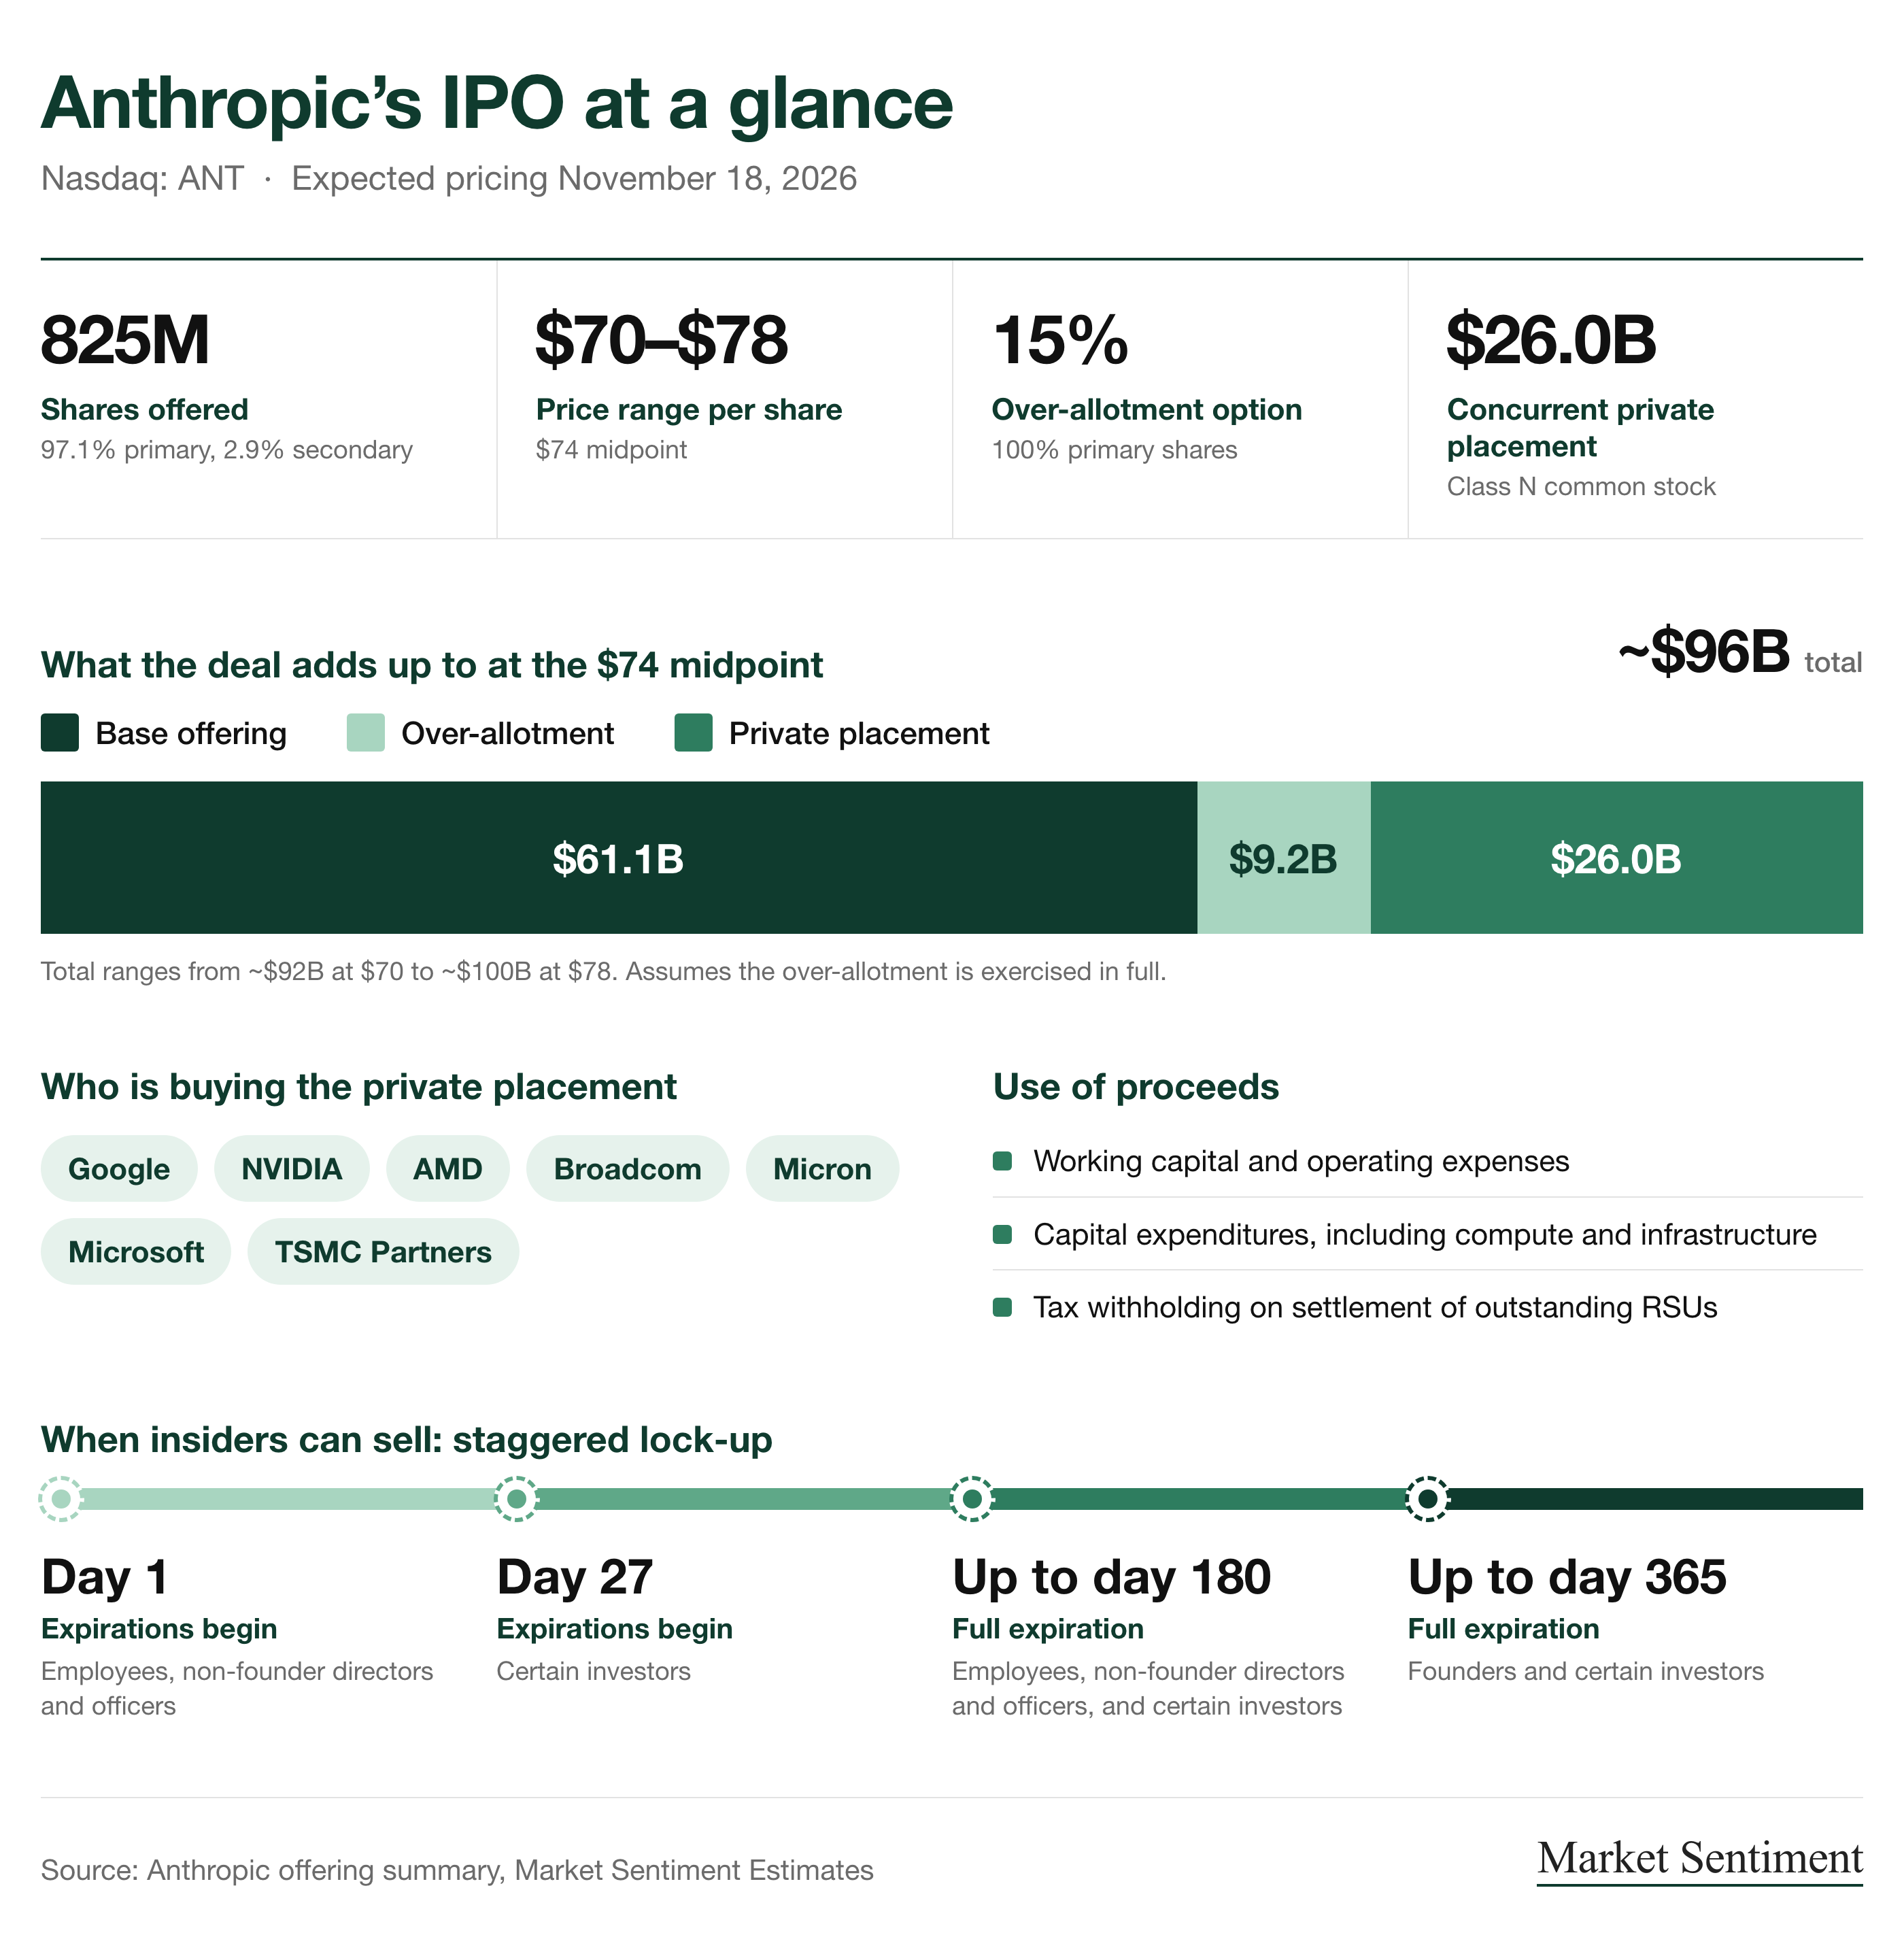
Here’s the quick rundown (from Anthropic’s roadshow):
When AI makes intelligence cheap, who stands to benefit? Join 46,000 other investors at Market Sentiment to make sure you don’t miss our next briefing.
Here’s how we are structuring this report:
Business Overview
Why Anthropic is a bet on AI acceleration
Anthropic’s moat
Financials and MS model
Risks — Governance structure, compute commitments, and competition
Our rating
Business Overview:
The company was founded in 2021 after a few researchers from OpenAI left because they disagreed with the direction and wanted to build a lab where safety and capability advanced together.
While we don’t usually place much importance on how a company markets its “founding story” (and how they are building it for the “good of humanity”), in this case, it worked out really well for them. Given that the entire company is founded on the premise of safety and alignment, it becomes a shoo-in for corporate clients who are worried about public perception and long-term safety.
Roughly 75% of Anthropic’s revenue comes from ~12,000 business customers who spend $100K or more. If you are a medical research firm or a bank, it’s easier to justify partnering with Anthropic than with any other firm. For example, both Bristol Myers (a global biopharmaceutical giant) and AIG have had a long-running partnership with Anthropic. From management’s perspective, any data breaches or AI hallucinations are much easier to justify if they happened with a company like Anthropic instead of a cheap Chinese open-source model.
While the S1/A does not split the revenue by product, what we know is:
Usage-based revenue is 79%, and subscriptions drive the other 21%
US contributes 71% of the revenue
Anthropic is a bet on continued AI acceleration
From a basic chatbot two years ago, Anthropic has now launched more than a dozen products competing with some of the biggest companies in the world.
Claude Code — GitHub Copilot (Microsoft), Cursor, OpenAI Codex
Claude Cowork — Microsoft 365 Copilot, Gemini in Google Workspace
Claude Sheets (beta) — Microsoft Excel, Google Sheets
Claude Design — Canva, Adobe, Figma
The TAM is obvious. But the interesting bit is that every step change in model capability unlocks a new product for Anthropic. From their roadshow slide, it’s clear that each year they can launch more products as underlying model capability improves.
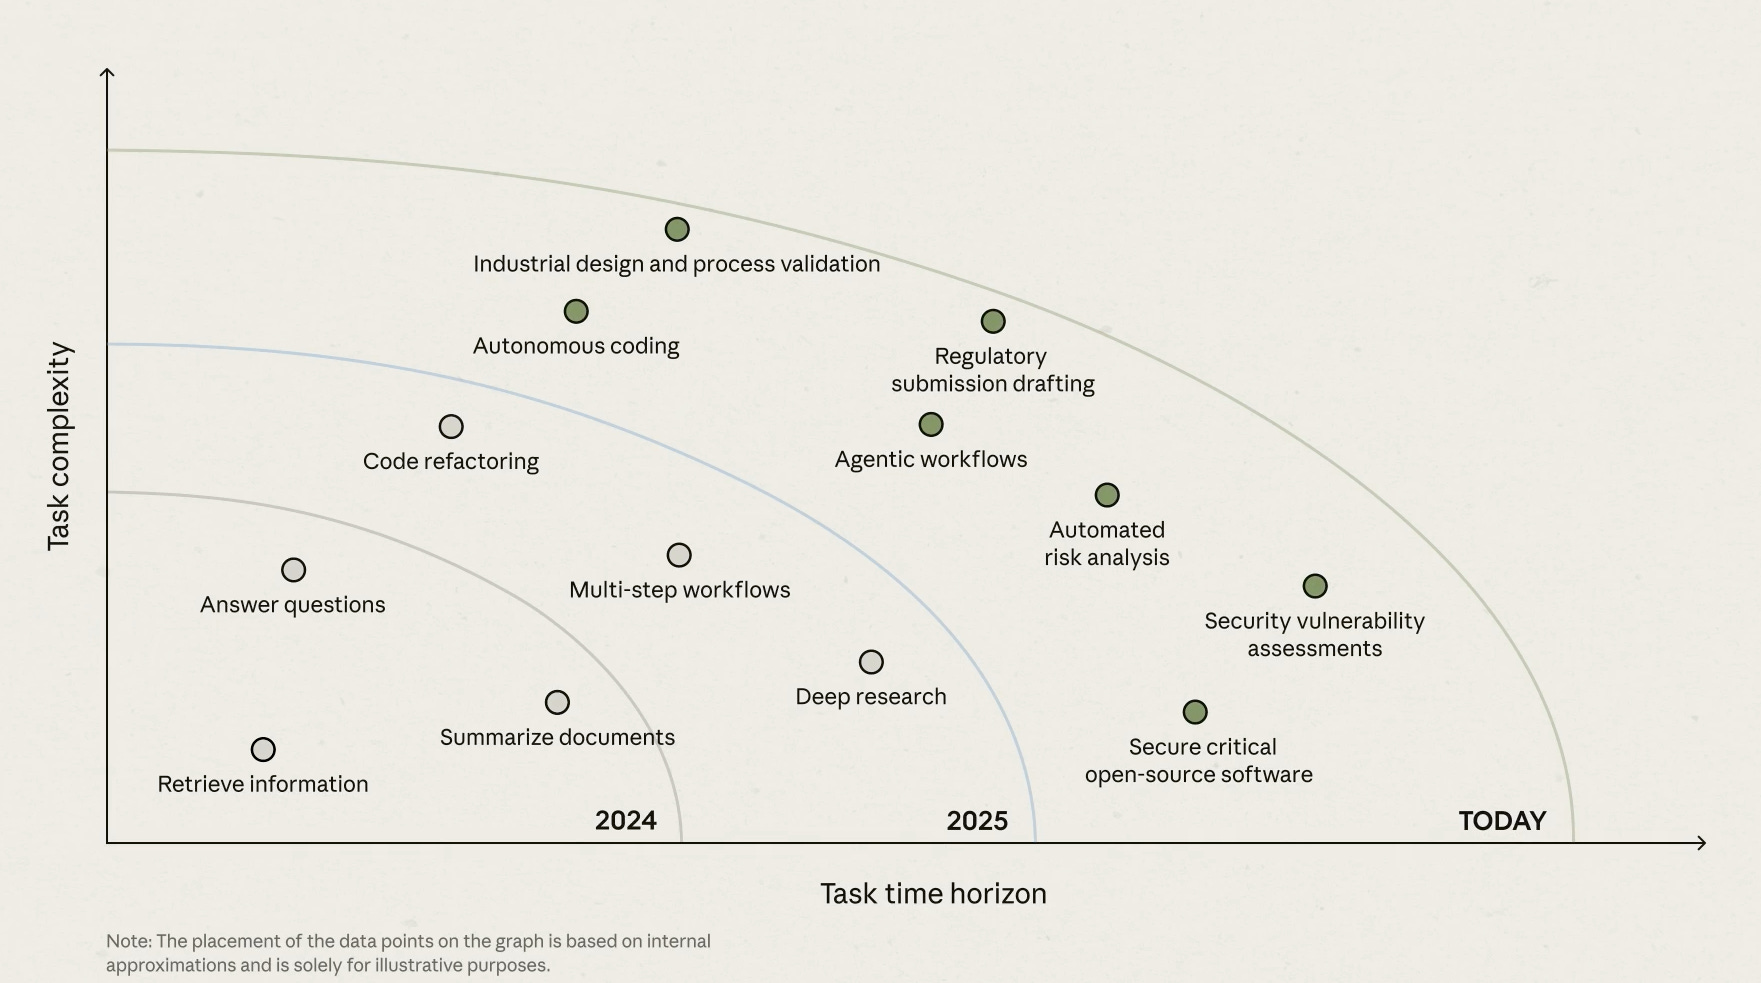
The rapidly expanding product base means Anthropic can upsell existing users.
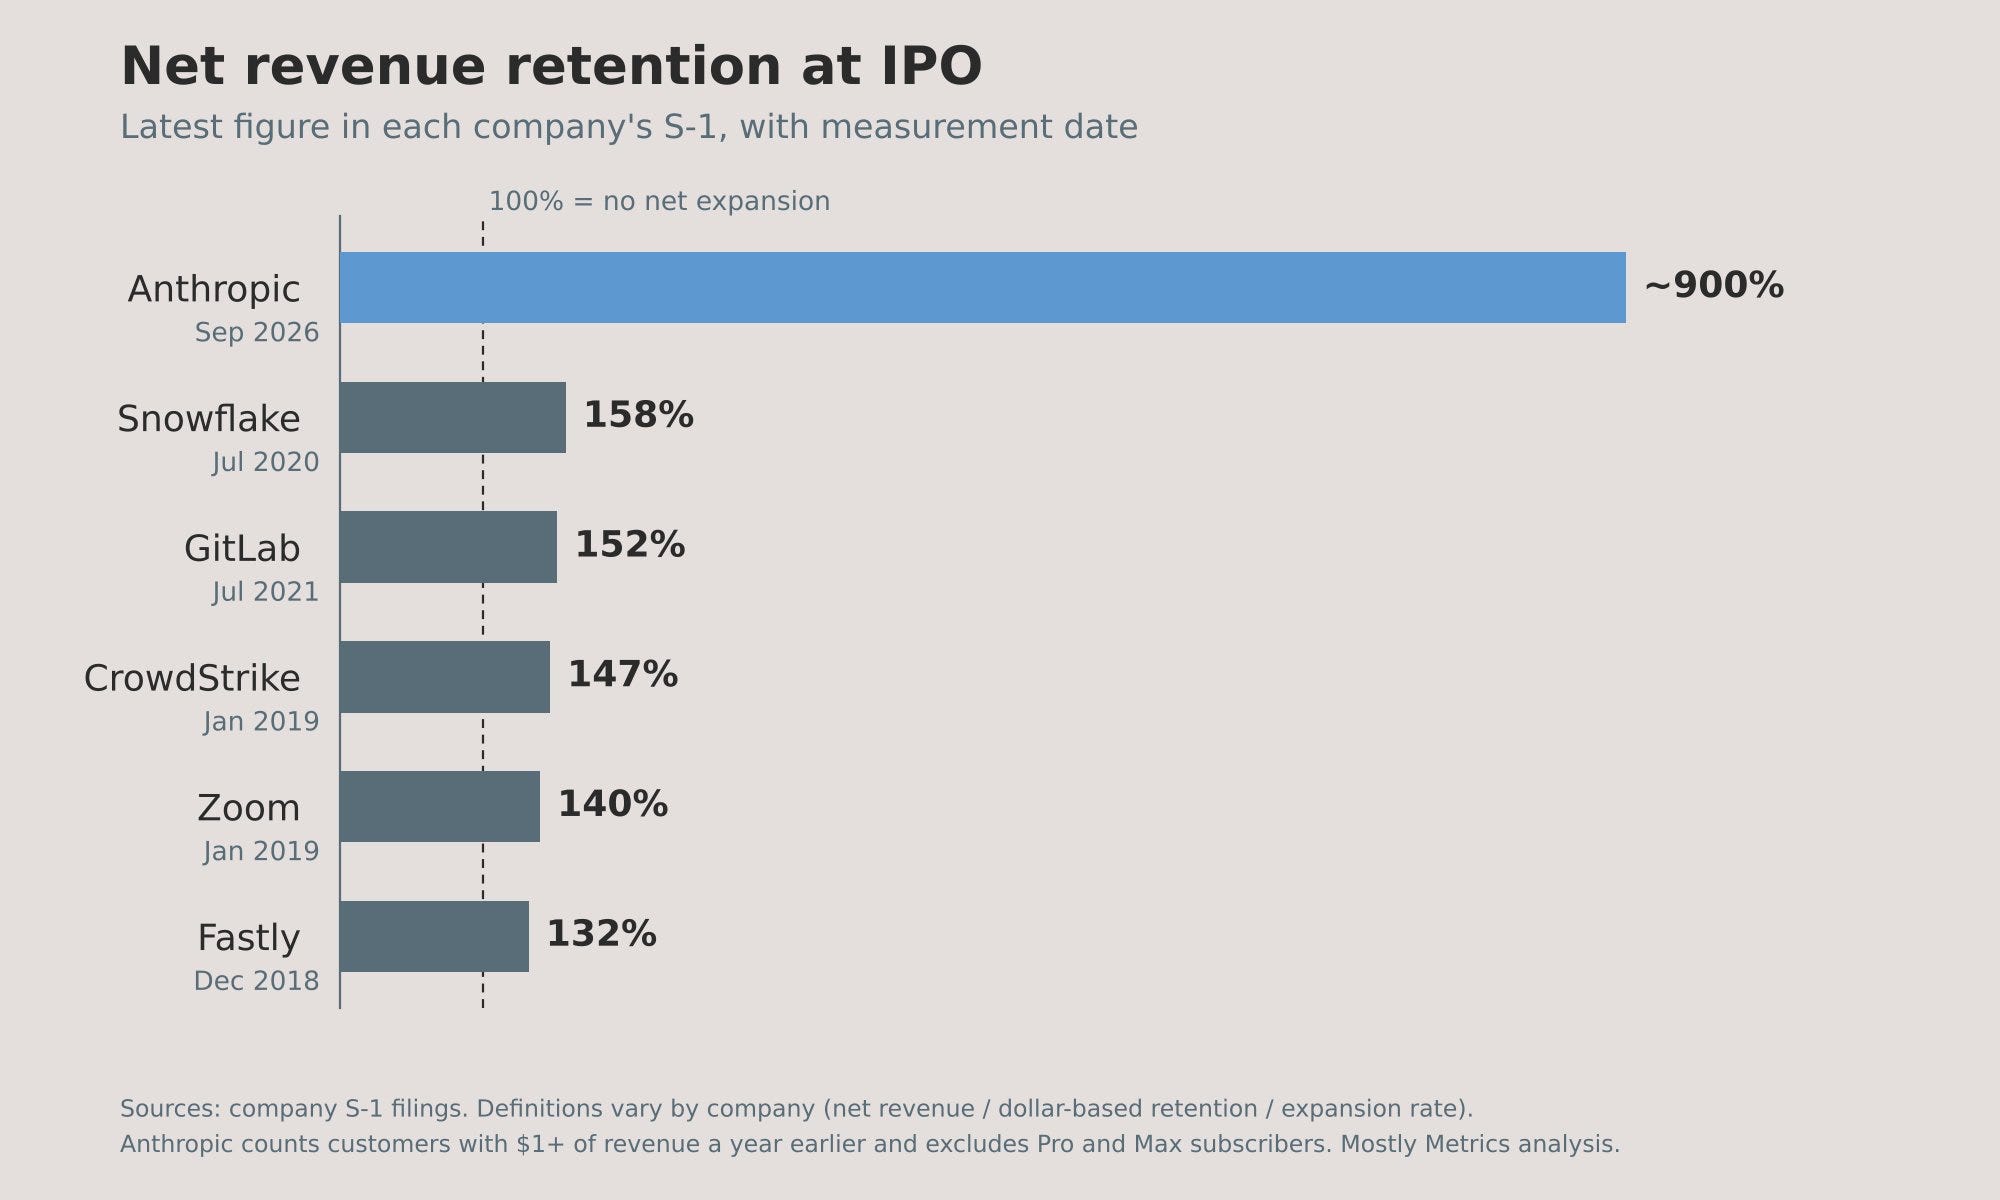
Net revenue retention (NRR) compares what a group of existing customers spends with you today to what the same group spent a year ago. If you are an incredible SaaS company like Snowflake or Datadog, your NRR would be above 100%, as customers tend to spend more the next year as the product embeds itself in the organization and finds more use cases.
The highest ever reported at IPO was for Snowflake at 158%.
Anthropic’s Net Revenue Retention is ~900%.
A customer that spent $100 with Anthropic in a quarter last year is now spending about $900 in that same quarter this year.
Even anecdotally, this plays out. Last year, our whole team switched from ChatGPT to Claude given the step change in performance. This year, most of our team is already on the Max plan, and our AI bill to Anthropic is easily 10x what it was last year.
The question now is how long Anthropic can keep this up. We all saw how Zoom flamed out after its meteoric rise during COVID.
Anthropic’s bet is that it has barely started: growth comes from capturing a bigger share of what its corporate clients already spend. Today its Fortune 500 customers put less than 0.1% of their total expenses toward Claude, on average. Even the ten biggest spenders among them are still under 1%.
Anthropic’s Moat
Other than the safety and privacy angle that we covered at the beginning, Anthropic’s moat rests on these three things:
Multi-silicon approach to compute: Anthropic trains and serves Claude on AWS Trainium, Google TPUs, NVIDIA GPUs, and AMD GPUs. The company treats all of it as one pool and routes each workload to the cheapest suitable hardware. What this means is that no single supplier can dictate terms and Anthropic can quickly turn on more capacity than any single vendor could deliver. On a slight tangent, this is a bear case for Nvidia’s margins.
Enterprise distribution: Anyone who has ever sold to enterprise will tell you that getting the foot in the door is half the work done. With over half of the Fortune 500 companies already spending >$100K with Anthropic, they have an incredible distribution base to build on. Going from 0 to $100k is 10x harder than going from $100K to $1M.
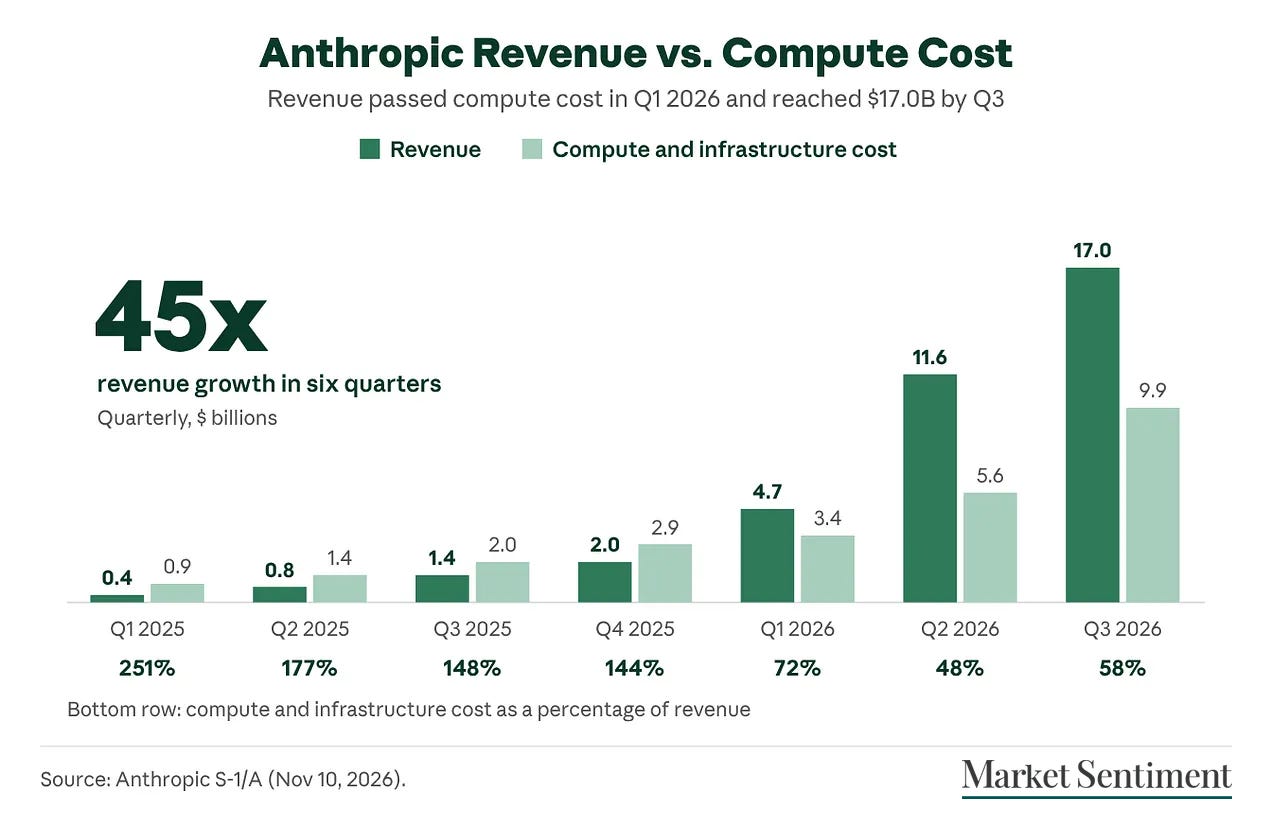
Claude is building Claude & compute multipliers: We should take this with a pinch of salt, but Anthropic just reported that over 90% of the code added to Anthropic’s codebase in September 2026 was written by Claude. Directionally, this is right, as revenue per employee has almost 5xed in the last year. Add to this the research improvements (what they have termed compute multipliers), which let them get more output from the same compute base: Q3 revenue grew 1,127% while compute costs grew 382%. If Claude keeps speeding up its own development, catching up gets harder for competitors.
Valuation: what $74 asks you to believe
So till now, it’s been nothing but good news. The tough part comes when we dig into the financials and comb through the risk section: